Stash
- Best for: Beginners who will contribute to an IRA or spend on a debit card and want investing, retirement, and banking in one app
- What Sets It Apart: 3% IRA match; stock rewards on card spending; one flat fee for every account
- Investments: Taxable, IRA, and custodial accounts; fractional shares
- Features: Smart Portfolio robo-advisor; Stock-Back debit card; $10,000 life insurance for ages 18 to 54
- Price: $12 a month or $108 a year; plus 0.25% a year on managed IRAs at any balance and on Smart Portfolios once they reach $1,000
- Pros: Match can cover the fee; easy automatic investing; no overdraft or minimum-balance fees
- Cons: Steep on small balances; card rewards capped at $10 a month; Fidelity offers the core investing for $0

Open Stash only if you’ll use its 3% IRA match or its Stock-Back card enough to cover the $108 annual fee, which takes about $300 a month into a self-directed IRA or $900 a month on the card. A managed IRA also charges 0.25% of its balance a year. Otherwise, Fidelity offers fractional shares and a no-fee IRA.
Stash is a subscription app for beginning investors that puts a brokerage account, an IRA, custodial accounts, and a rewards debit card under one flat fee. It pays for itself only for members who put real money into its IRA or run their spending through its card.
Key Features
- The Stash Plan at $12 a month, or $108 a year billed annually1
- An extra 0.25% a year on managed IRAs at any balance, and on Smart Portfolios (its robo-advisor accounts) once they reach $1,0002
- A 3% match on new IRA contributions, capped at 3% of the annual IRA limit ($225 at the standard limit)4
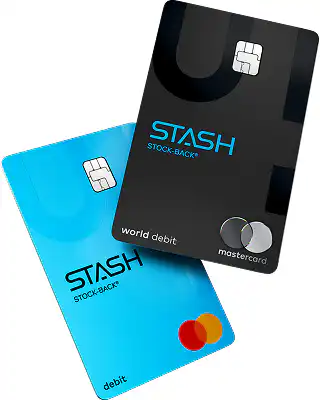
- A Stock-Back debit card paying 1% in stock on the first $1,000 of monthly spending, up to 3% at bonus merchants, then 0.125% once rewards reach $10 for the month3
- $10,000 of group life insurance for members ages 18 to 54
Pros
- The IRA match alone can cover the annual fee for steady contributors4
- Automatic investing, round-ups, and fractional shares make small deposits easy
- Custodial accounts for kids at no extra cost6
- Banking with no overdraft or minimum-balance fees3
- A $25 bonus for new members who invest $55
Cons
- For a $50-a-month investor, the fee equals 18% of first-year deposits on the annual plan, or 24% billed monthly (our math)
- Boosted card rewards top out at $10 a month, or $120 a year, before dropping to 0.125%
- The match stops when you cancel, and withdrawals within four years can forfeit it4
- Robinhood Gold pays a 3% IRA match for $5 a month, but requires five years in the IRA, against Stash’s four
- Fidelity offers fractional shares, a no-fee IRA, and a robo-advisor free under $25,000
On the annual plan, Stash pays for itself once you contribute about $300 a month to a self-directed IRA or spend about $900 a month on its card, by our math. A managed IRA needs more than $300 a month, since its 0.25% fee grows with the balance. Below those amounts, the fee outweighs the rewards, so open a free Fidelity account.
Learn more about Stash or see how it compares to the best micro-investing apps.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: